Pillsbury & Coleman successfully demurred to an insurance carrier’s claim that its excess insurance policy should be reformed to reflect more limited coverage that would have barred the insured’s claim for delay in completion benefits. The insured, a developer of a large condominium project, suffered tens of millions in damages when its condominium building burned to the ground. Following exhaustion of its primary coverages, the insured made a claim to its excess carrier for additional Delay in Completion benefits. The carrier refused, claiming in part that its policy did not reflect the true intent of the parties and that the policy should be reformed to preclude coverage for Delay in Completion.
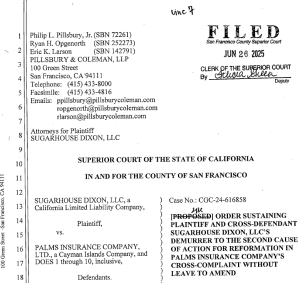
Pillsbury & Coleman successfully demurred to that claim. Our position was that reformation was precluded by the plain terms of the policy. In particular, policy Section 17 provided that, “Notice to or knowledge possessed by any agent or other person will not constitute a waiver or change in any part of this Policy or stop us from asserting any rights under the terms of our Policy. The terms of this Policy cannot be waived or changed, except by endorsement issued to form a part of this Policy.” (Italics added) The Court agreed, holding that Section 17 plainly and unambiguously precluded the insurance carrier’s reformation claim. This ruling streamlined the case, allowing the parties and the Court to focus on the remaining legal issues and settlement.
A copy of the Court’s Order can be accessed here.